- Competition in Health Insurance, 2026 update
- Competition in Pharmacy Benefit Manager Markets and Vertical Integration with Insurers: 2026 update
- Competition in Hospital Markets, 2026 update
- Research on the Anthem-Cigna and Aetna-Humana mergers
- Research on the UnitedHealth-Sierra Health merger
- Previous policy research perspective on PBMs and vertical integration with insurers
The Division of Economic and Health Policy Research (Division) conducts independent research on competition in health insurance, pharmacy benefit manager (PBM) and hospital markets.
A key question of public policy is whether health insurance markets are competitive or whether insurers have market power, which can cause competitive harm. One of the Division's most significant efforts is the annual Competition in Health Insurance (CHI) study. This annually updated study is the only publication of its kind. It is based on an analysis of unique enrollment data from a single data source for health insurers in all states and metropolitan statistical areas (MSAs) of the U.S. The Division has also conducted analyses of past and proposed mergers among health insurers.
The Division also conducts research on PBM markets. Using unique enrollment data on drug coverage lives from the same data source used for its CHI study, it publishes research as part of its Policy Research Perspectives (PRP) series that assesses competition in PBM and vertical integration of insurers with PBMs. Finally, it also conducts research on hospital markets. Using data from the American Hospital Association (AHA), it assesses competition in hospital markets also as part of its PRP series.
A useful indicator of competition and market power is market concentration. The U.S. Department of Justice (DOJ) and the Federal Trade Commission (FTC) examine market shares and market concentration in their evaluation of proposed mergers between firms. They describe how they will analyze mergers in their 2023 Merger Guidelines. The Division's research analyzes market concentration to assess market competition.
Competition in Health Insurance, 2026 update
The 2026 update to Competition in Health Insurance: A Comprehensive Study of U.S. Markets (PDF) presents new 2025 data on the degree of competition in commercial and Medicare Advantage health insurance markets. It is intended to help identify areas where consolidation involving health insurers may cause competitive harm to consumers of health insurance and consumers and suppliers of healthcare.
The study reports the two largest insurers’ market shares and the concentration levels (HHIs) for state- and MSA-level markets in the U.S. It finds that the vast majority of health insurance markets remain stubbornly highly concentrated. Therefore, they are prone to the exercise of insurer market power and are at risk for insurer mergers to substantially lessen competition and cause competitive harm.
Key findings from the 2026 update include:
Commercial markets
- The average MSA-level market HHI rose from 3322 in 2014 to 3409 in 2025—an increase of 87 points. However, the exchanges tempered that increase. Excluding the exchanges, the average HHI went up by 401 points.
- Ninety-five percent (372) of MSA-level markets were highly concentrated (HHI>1,800) in 2025, based on the 2023 Merger Guidelines.
- In 90% (347) of MSAs, at least one insurer held a commercial market share of 30% or greater, and in 47% (180) of MSAs, one insurer's share was at least 50%.
- A Blue Cross Blue Shield (BCBS) insurer had the largest state-level market share in 43 states.
- A BCBS insurer had the largest MSA-level market share in 84% (323) of MSAs.
- Elevance Health (BCBS) had the largest MSA-level market share in 22% (83) of MSAs.
- Nationally, UnitedHealth Group was the largest commercial health insurer. Collectively, however, BCBS insurers would be the largest with a combined commercial market share of 42%. Centene was the largest insurer in the exchanges.
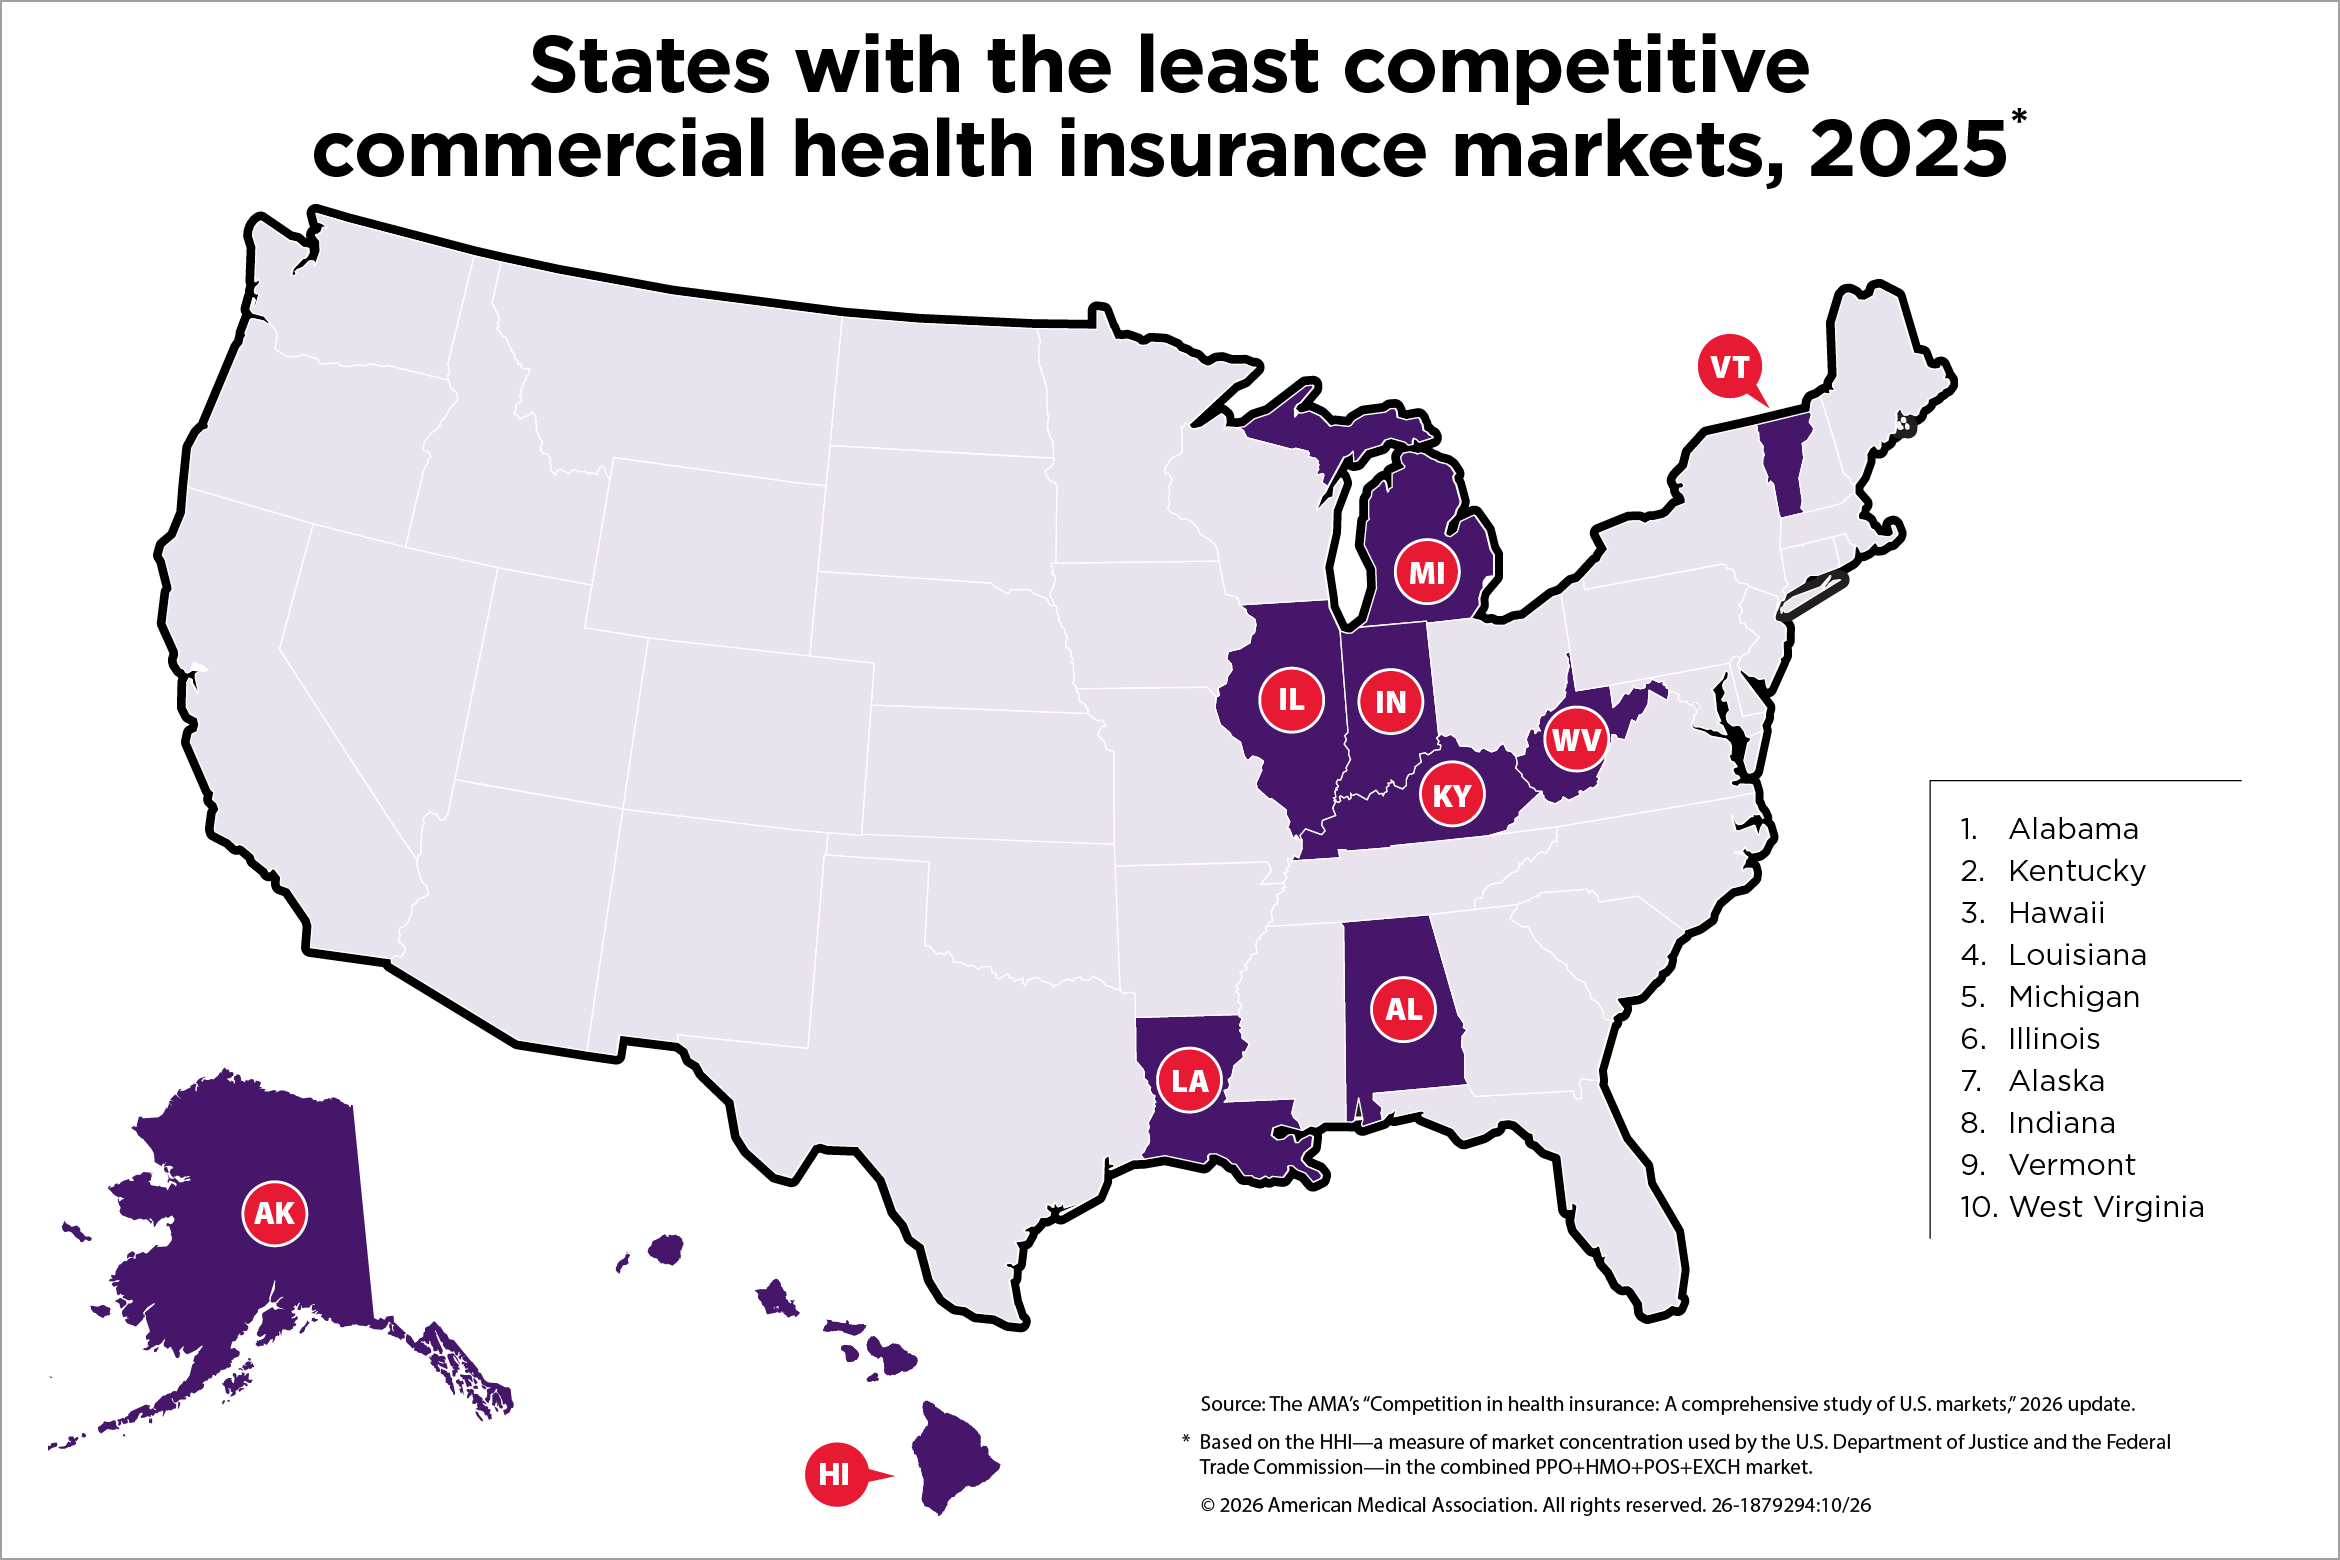
Maps from the study
- Ten states with the least competitive commercial health insurance markets, 2025 (PDF)
- Ten states with the least competitive exchanges, 2025 (PDF)
- Market share of the largest commercial insurer in each state, 2025 (PDF)
Medicare Advantage markets
- MA markets were highly concentrated on average, with an HHI of 3085—down from 3923 in 2017. However, after decreasing each year up to 2024, market concentration went up for the first time in 2025—albeit modestly by 28 points.
- Ninety-seven percent (372) of MSA-level markets were highly concentrated (HHI>1,800) in 2025—down slightly from 99% in 2017.
- In 88% (340) of MSAs, at least one insurer held a market share of 30% or greater, and in 25% (97) of MSAs, one insurer's share was at least 50%.
- Nationally, UnitedHealth Group was the largest health insurer with a 30% share in 2025—up from 25% in 2017.
- UnitedHealth Group had the largest MSA-level market share in 44% (171) of MSAs, and Humana was the biggest in 20% (76) of MSAs.
Maps from the study
- Ten states with the least competitive Medicare Advantage markets, 2025 (PDF)
- Market share of the largest Medicare Advantage insurer in each state, 2025 (PDF)
Competition in Pharmacy Benefit Manager Markets and Vertical Integration with Insurers: 2026 update
Using 2022 and 2024 data on prescription drug plan (PDP) lives and the pharmacy benefit managers (PBM) used by insurers to perform five PBM functions, this study titled Competition in Pharmacy Benefit Manager Markets and Vertical Integration with Insurers: 2026 Update (PDF) assesses competition in PBM markets and the extent of vertical integration between insurers and PBMs. It also assesses competition in PDP insurance markets.
Key findings from the paper include:
Competition in PBM markets
Competition in PBM markets is assessed using the three functions for which insurers most prevalently use an external PBM: rebate negotiation, retail network management and claims adjudication. The findings are similar across those functions, so the findings below focus on rebate negotiation.
- The four largest PBMs collectively had a 75% share of the national PBM market in 2024—up significantly from 70% in 2022.
- OptumRx was the largest PBM nationally in 2024 with a 23% market share—up from 21% in 2022. Very closely behind is Express Scripts with a share of 23%—an increase from 17% in 2022. CVS/Caremark fell from being the largest PBM in 2022 to the third largest with an 18% share in 2024. Prime Therapeutics had an 11% share, making it the fourth-largest PBM.
- Locally, the average PBM market is highly concentrated (HHI>1800), and it became more concentrated between 2022 and 2024.
- The average HHI across PDP regions was 2574 in 2024—up from 2410 in 2022.
- The vast majority (94%) of PBM markets were highly concentrated in 2024—up from 82% of markets in 2022.
Vertical integration of PBMs and insurers
- In 2024, 69% of PDP lives at the national level were covered by an insurer that is vertically integrated with a PBM—down from 72% in 2022.
- There is variation in the extent of vertical integration by payer type.
- Sixty-seven percent of commercial PDP lives were vertically integrated, compared to 73% in Medicare Part D.
- Across PDP regions, an average of 67% of people were covered by a vertically integrated insurer.
- There is wide variation across PDP regions, with some having little vertical integration, while others are almost entirely vertically integrated.
- The 10 largest PBMs in the U.S. share ownership with insurers.
Competition in PDP insurance markets
- Across PDP regions, PDP insurance markets are highly concentrated on average, with HHIs of 2578 in commercial markets, 2406 in Medicare Advantage PDP markets, and 2214 in standalone PDP markets.
- UnitedHealth Group is the largest PDP insurer in the U.S. in the commercial PDP (14% share) and Medicare Advantage PDP (30%) markets, and third largest in the standalone PDP market (18% share).
- The second, third and fourth-largest commercial insurers are Kaiser, Cigna and Elevance Health, each with 10% shares.
- Humana is the second-largest Medicare Advantage PDP insurer with a 19% share.
- Centene became the largest insurer in the standalone PDP market with a 28% share in 2024—up significantly from 18% in 2022.
Competition in Hospital Markets, 2026 update
Using 2013-2024 data from the American Hospital Association, this study titled Competition in Hospital Markets, 2026 update (PDF) analyzes shares of hospitals and market concentration (HHIs) levels in MSA-level markets across the U.S. It also estimates the extent of hospital membership in systems, and it presents the two largest hospital market shares and HHIs in each MSA for 2024. Market shares pertain to a system if a hospital belongs to one. Finally, the study reports the 10 largest hospital systems by market share at the national level.
Key findings from the study include:
- Ninety-nine percent (394) of MSA-level hospital markets were highly concentrated (HHI>1,800) in 2024, based on the 2023 Merger Guidelines.
- The weighted average HHI across MSA-level markets was 4,205 in 2024—up from 3,722 in 2013.
- In 97% (387) of MSAs, at least one hospital held a market share of 30% or greater in 2024.
- In 78% (310) of MSAs, one hospital's share was at least 50% in 2024—up from 70% in 2013.
- In 2024, a single hospital’s market share was 70% or greater in 44% (174) of MSAs—compared 37% of markets in 2013.
- In 2024, 81% of hospitals were members of systems—up from 70% of hospitals in 2013.
- The largest hospital system had a national market share of 6.7% and 150 hospitals in 2024, while the second largest system had a share of 2.6% and 113 hospitals.
Research on the Anthem-Cigna and Aetna-Humana mergers
AMA conducted analyses (see below) of the likely impact that the blocked Anthem-Cigna and Aetna-Humana mergers would have had on commercial markets and of the Aetna-Humana merger on Medicare Advantage markets. The analyses found that each of the mergers would have likely been anticompetitive in numerous markets across the U.S.
- Effects of Anthem-Cigna merger on commercial markets (PDF)
- Effects of Aetna-Humana merger on commercial markets (PDF)
- Effects of Aetna-Humana merger on Medicare Advantage markets (PDF)
Read more about the AMA’s successful efforts to block the Anthem-Cigna and Aetna-Humana mergers.
Research on the UnitedHealth-Sierra Health merger
This paper (PDF) examines the association between health insurance market concentration and prices. It is a case study of the 2008 merger between UnitedHealth Group and Sierra Health Services.
It found that health plan premiums in Nevada markets increased by 13.7% after the merger. The findings suggest that the merging parties exploited the market power gained from the merger.
Previous policy research perspective on PBMs and vertical integration with insurers
Using 2020 and 2021 data on commercial drug coverage lives and the PBMs used by insurers to perform five PBM functions, Competition in Commercial PBM markets and Vertical Integration of Health Insurers with PBMs: 2023 Update (PDF) presents a descriptive analysis of PBM markets and the provision of PBM services to health insurers. It reports the ten largest commercial PBMs and drug insurers in the U.S. at the national level. The paper also summarizes concentration levels (HHIs) in state- and MSA-level PBM markets and presents the two largest PBM market shares and HHIs for all state-level markets. Finally, it quantifies the extent of vertical integration of health insurers with PBMs.